Mercuryo’s Q3 2026 research shows Asia accounted for 39.3% of stablecoin purchase value on BNB Chain, while Apple Pay and Google Pay represented 69.5% of purchases, highlighting the growing role of mobile payments and local currencies in digital asset adoption
Stablecoins are increasingly being used beyond cryptocurrency trading, with growing interest in cross-border transfers, dollar-denominated assets and everyday payments. Mercuryo’s latest research with BNB Chain found that 77.4% of stablecoin transfers were below $100, while transactions worth $10,000 or more accounted for 66.2% of total transfer value. FinTech Business Asia speaks with Arthur Firstov, Chief Business Officer at Mercuryo, about stablecoin adoption across Asia, mobile payment preferences, cross-border transaction costs, self-custody wallets and the challenges of distinguishing payment activity from cryptocurrency trading
Q. What does the contrast between small transfers and large transaction values reveal about stablecoin use, and where are the strongest growth opportunities?
The findings show that stablecoins are no longer serving a single purpose. In the past, they were primarily used as a way to hold value between trades, particularly for people taking positions in Bitcoin and other digital assets. Today, we are seeing the same infrastructure support a much broader range of financial activity.
The fact that 77.4% of stablecoin transfers on BNB Chain in Q3 2026 were below $100 suggests that a significant proportion of activity takes place at relatively small transaction sizes. This is consistent with use cases such as everyday transfers, remittances, and moving money between wallets. At the other end of the spectrum, transactions of $10,000 or more accounted for 66.2% of total transfer value, demonstrating the role stablecoins play in moving larger amounts of capital across digital asset markets.
What is particularly interesting is that these two forms of activity can coexist on the same network. Stablecoins offer the flexibility to move relatively small amounts of money as well as facilitate substantial transfers of value, without being restricted by traditional banking hours or the same settlement processes.
For Mercuryo, the opportunity is to make both sides of this market more accessible. On the consumer side, that means simplifying the process of converting fiat currency into digital assets and back again. On the institutional side, there is an opportunity to provide the infrastructure that allows businesses and financial platforms to integrate digital assets into their existing services.
Cross-border payments are another important area of potential growth. Where traditional payment systems involve multiple intermediaries, stablecoins can provide an alternative way to move value across borders. However, the technology itself is only one part of the equation. Users still need reliable ways to enter and exit the ecosystem, convert between currencies, and access their funds.
In my view, the strongest opportunities will be where stablecoins replace something that works poorly today, and slow, intermediary-heavy cross-border settlement is the clearest example. Trading will continue to matter, but it is no longer the whole story.
Q. Asia accounted for 39.3% of stablecoin purchase value through Mercuryo on BNB Chain. What is driving demand, and which markets or corridors offer the greatest opportunities?
Asia accounted for 39.3% of stablecoin purchase value through Mercuryo on BNB Chain in Q3 2026, making it the largest regional market in our research, ahead of Europe at 33.4%. This is an important indicator of the region's significance within the digital asset ecosystem.
One of the key findings from the report is that 70% of the value used to purchase dollar-denominated stablecoins through Mercuryo was paid in currencies other than the US dollar. This demonstrates that stablecoin adoption is not limited to people who already hold dollars. Users are converting from their local currencies into dollar-denominated digital assets, highlighting the importance of accessible fiat-to-crypto infrastructure.
The 70% figure is, in my view, the most revealing number in the report. Seven-tenths of the value spent on dollar-denominated stablecoins was funded in another currency, which tells us that demand is being driven in large part by people holding local currencies who want access to the dollar. Combined with Asia's lead at 39.3%, ahead of Europe at 33.4%, it is reasonable to expect that much of the demand in the region is local-currency-to-dollar demand, rather than activity from people who already hold dollars.
There are several potential drivers behind this demand. Asia is home to diverse digital asset markets, with different levels of financial infrastructure, consumer adoption, and access to international payment services. In some markets, users may be interested in accessing dollar-denominated assets, while in others, stablecoins may offer an additional option for transferring value across borders or participating in the digital economy.
However, it is important not to treat Asia as a single market. Consumer behaviour, local payment preferences, regulatory frameworks and banking infrastructure vary considerably between countries. The requirements for serving a user in Singapore can be very different from those in Indonesia, Vietnam or the Philippines.
From a commercial perspective, we see opportunities wherever there is meaningful demand for digital assets and a clear need for better connections between local payment systems and blockchain networks. Cross-border payment corridors are particularly interesting because they involve multiple currencies, payment providers, and settlement processes. Stablecoins can potentially simplify parts of that journey, provided users have dependable on- and off-ramps at both ends.
The priority for infrastructure providers is therefore not simply to expand into as many markets as possible. It is to understand local customer needs, support relevant payment methods and build compliant services that make accessing digital assets straightforward.
Our research provides a useful starting point by showing where purchase activity is already taking place. Further country-level and corridor-level analysis is needed to determine precisely where the strongest commercial opportunities lie. The strongest signal is the pairing of a large Asian share with a heavily non-USD funding base, and that is where I expect a corridor-level view to be most revealing. What is clear is that the ability to connect local currencies with global digital asset networks will be an important part of the next stage of stablecoin adoption.
Q. Apple Pay and Google Pay accounted for 69.5% of stablecoin purchases, while 87.2% of purchases with recorded device information were made on mobile phones. What does this tell us about accessibility and adoption?
For me, one of the most significant findings is how closely stablecoin purchasing behaviour is beginning to resemble the way people already pay for things online.
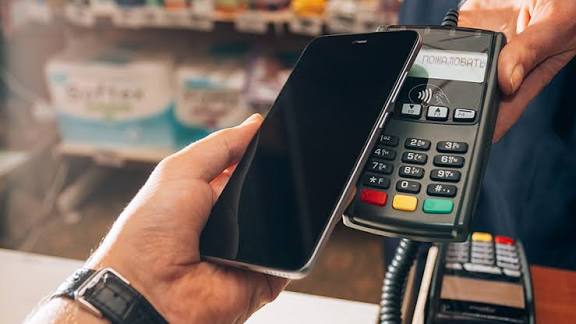
Apple Pay and Google Pay accounted for 69.5% of stablecoin purchases through Mercuryo in Q3 2026, while 87.2% of purchases with recorded device information were made on mobile phones. These figures demonstrate the importance of familiar payment methods and mobile-first experiences when bringing digital assets to a wider audience.
The industry has spent years debating wallets, protocols, and chains. The data suggests customers care far less about any of that than about paying the way they already do. Apple Pay and Google Pay are not a side feature of stablecoin adoption. On this evidence, they are the main route into it.
That is an important distinction. Mainstream adoption does not necessarily require every consumer to become an expert in blockchain technology. It requires the technology to become accessible through products and experiences that people understand.
If consumers can acquire stablecoins as easily as they make other online purchases, it becomes more practical to explore what they can do with those assets afterwards, whether that involves transferring value, accessing decentralised applications or making payments through supported services.
Of course, an easy purchase experience is only the starting point. Users also need confidence in the security of the service, transparency around fees and a clear understanding of what they are buying. Stablecoins remain cryptoassets, with risks that differ from holding money in a bank account.
The opportunity is to combine the efficiency of blockchain technology with the familiarity and reliability people expect from established payment services. When that happens, digital assets become less of a standalone activity and more of an integrated part of the financial products people use every day.
Q. With a median BNB Chain stablecoin transfer fee of $0.0068, how much of the cost advantage reaches end users, and what barriers remain before stablecoins can compete with traditional cross-border payments?
The median transfer fee of $0.0068 on BNB Chain is a compelling illustration of the efficiency that blockchain infrastructure can offer. Moving value on-chain can be extremely inexpensive, particularly when compared with payment processes that involve multiple intermediaries.
However, it is important to distinguish between the cost of transferring a stablecoin on a blockchain and the total cost a customer pays to move money from one currency or payment system to another.
The network fee represents only one part of the journey. A user may also incur charges when purchasing stablecoins with fiat currency, converting between assets, or selling stablecoins back into fiat. Foreign exchange spreads, payment processing fees, and the costs associated with different providers can all influence the final amount received.
The report measures the on-chain cost of moving stablecoins, and on that measure, the figure is very low. What it cannot tell us is how much of that saving reaches the end user, because the network fee is only one part of what a customer ultimately pays. How much of the advantage is passed on will depend on the services and providers involved in each transaction.
For that reason, I would be cautious about comparing stablecoins with traditional cross-border payments on the strength of the network fee alone. A low on-chain cost is a strong starting point, but whether it translates into a better outcome for users depends on the full cost of the journey, which this research does not measure.
Consumer protection and trust are equally important. Users need clarity on fees, exchange rates, settlement times, and the risks associated with the stablecoin itself. Stablecoins are designed to track the value of a reference currency, but that does not eliminate issuer, redemption or other risks.
Q. Self-custody wallets accounted for 59.5% of stablecoin purchase value through Mercuryo. How is this influencing product strategy, and what challenges does it create around security, compliance, and customer protection?
The report found that 59.5% of stablecoin purchase value through Mercuryo went to self-custody wallet channels. It also found that 59.8% of our off-ramp value originated from self-custody wallets. These findings reinforce the importance of self-custody within the digital asset ecosystem.
Self-custody gives users direct control over their digital assets rather than requiring them to rely on a centralised platform to hold those assets on their behalf. For many users, that level of control is an important part of the appeal of blockchain technology.
From an infrastructure perspective, it means payment services need to work effectively with the wallets people already use. For Mercuryo, this reinforces the importance of providing flexible infrastructure that can be integrated into third-party platforms. Our role is to help connect traditional payment methods with the digital asset ecosystem, making it easier for users to move between fiat and crypto within the products they choose to use.
At the same time, self-custody introduces responsibilities that cannot be overlooked. Users are responsible for protecting their private keys and recovery credentials, and losing access can mean losing access to their assets permanently. Transactions sent to an incorrect address may also be difficult or impossible to reverse.
Customer protection requires a balance. We need to preserve the benefits of user control while making sure that people understand how the products they use work, what risks they face, and what recourse is available if something goes wrong.
This is where regulated infrastructure earns its place. A customer may hold their own keys, but the point at which fiat enters or leaves the system is still a regulated activity. Identity verification, sanctions screening, and transaction monitoring therefore sit at the on-ramp and off-ramp, even though the assets themselves sit in the user's wallet. Self-custody changes where assets are held, not the obligation to know who we are dealing with and where the funds come from.
Risk management is the other half of the picture. A confirmed blockchain transaction cannot be reversed, so the realistic window for protecting a customer is before the payment completes. Monitoring for unusual patterns, such as activity linked to high-risk wallet addresses, rapid movement of funds or signs of fraud and scams, allows a provider to flag or stop a transaction at that point, rather than trying to fix it afterwards.
I do not see self-custody and regulation as being in tension. Users keep control of their assets and their choice of wallet, while the regulated payment layer provides the checks and safeguards around the edges. Done well, the two reinforce each other: users get freedom, and the wider ecosystem gets the standards it needs to grow sustainably.
Q. The research found that 64.3% of stablecoin value on BNB Chain had moved within the previous 30 days. How can we distinguish genuine payment activity from trading, and what is needed for mainstream adoption?
I think the most valuable part of this research is how it was built. Mercuryo contributed fiat-side data on stablecoin purchases and sales through our infrastructure: who is buying and selling, which payment methods they use, and which currencies fund the purchase. BNB Chain contributed the on-chain view of how value was held, transferred, and settled. Together, the two datasets let us follow stablecoins from a card or bank account into a wallet and back out again, a joined-up picture that neither side could produce alone.
The finding that 64.3% of stablecoin value on BNB Chain had moved within the previous 30 days suggests that a substantial proportion of value was actively circulating rather than remaining stationary. This is an interesting indicator of network activity, but it is important to be precise about what it tells us.
On-chain data can show when value moves, how much is transferred, and which addresses are involved. However, a transfer alone does not necessarily tell us why it happened. The same stablecoin can be used to facilitate a payment, move funds between a user's own wallets, settle a trade, or provide liquidity to a digital asset market.
Distinguishing between these activities requires looking beyond transaction size or frequency. It involves examining on-chain patterns alongside other available information, including the type of service involved and, where appropriate, the fiat on- and off-ramp activity associated with a transaction. This is where the combined dataset matters most: fiat context is exactly what on-chain data lacks when it comes to telling a payment from a trade.
Even with this combined view, we should not assume that every small transfer represents a remittance or that every large transfer represents institutional activity. The data reveals patterns consistent with different use cases, but determining the precise purpose of individual transactions requires additional evidence.
Stablecoins are already being used for a range of purposes, from small-value transfers to substantial movements of capital. The next stage is to build the infrastructure, user experiences, and regulatory foundations that allow these capabilities to serve a much broader range of everyday financial needs.
At Mercuryo, we see our role as helping bridge the gap between traditional finance and digital assets. The easier it becomes for people and businesses to move between fiat currencies and blockchain-based value, the more practical stablecoins become as part of the wider financial ecosystem.